Using Your Home Equity to Stay Just a Little Bit Longer
Lisa Manwaring • July 5, 2018

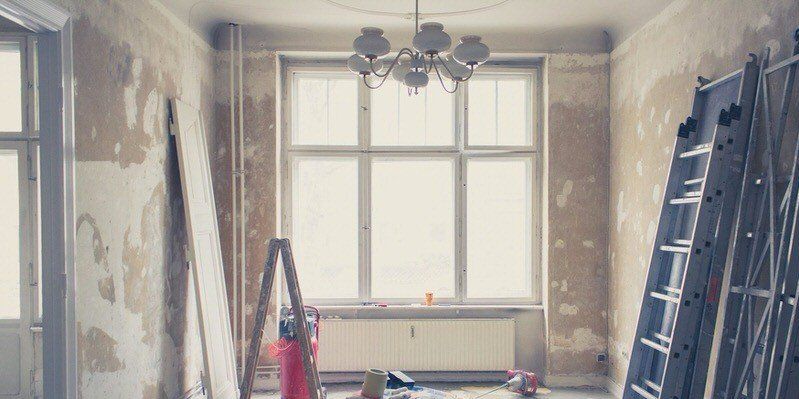
Last month, the article "Can't find the Perfect Property in Your Price Range" was published on the blog, where the purchase plus improvements program was outlined as a way to buy and renovate a property at the same time. If you are looking to buy a new home, but can't find something you love, this article is certainly worth a read! But what if you don't want to move? What if you like the place you're in, but it could use a few upgrades? Well, here are some ways you might be able to stay, just a little bit longer!

Introducing the mortgage refinance, and the refinance plus improvements. Both products allow you to leverage your home equity for home improvements.

Refinance

If your mortgage balance is less than 80% of your property's value, then assuming you qualify (given the latest changes to mortgage qualification), you can access the equity built up in your home to that 80% level. Lenders will typically ask what the funds are going to be used for, however you won't have to prove anything after the fact. You should be able to access up to $200,000. Assuming you have the equity, a refinance is a really great way to access funds for various reasons, here are just a few:

  • Renovate your house
  • Consolidate your high-interest debts
  • Help your children pay for education
  • Top up your investments
  • Access money for a downpayment on a vacation property
  • Start a new business (just don't quit your day job)
    … Or any combination of the above

But what happens if you want to do some renovations to your property, but your mortgage balance is more than 80% of your home's value? That's where the refinance-plus-improvements comes in.

Refinance-Plus-Improvements

Although guidelines will vary from lender to lender, the refinance-plus-improvements will allow you to access up to 80% of your property's existing value, plus the cost of the renovations. Most lenders will consider 10% of the initial value of the home, or $40,000, whichever is less, to be included for renovations. So when you take the existing value of your home and add the suggested cost of the renovations, this becomes the improved value. The mortgage is then based on the improved value, instead of your existing value.

However, the catch here is that the renovations have to increase the value of your home accordingly. And the lender wants to ensure that the renovations have been completed, and the value of the property has been increased before they will actually let you have access to the money. So, although the cost of the renovations can be added to the mortgage, it's your responsibility to pay for the renovations up front, and once the improved value is substantiated by an appraisal, then the funds will be released from the lawyer's trust account.

Securing a purchase-plus-improvements is certainly a little more tricky than executing on a refinance, but if you don't have enough equity saved up, this might just be the product that allows you to access your home equity in order to increase the value of your home, and give you a nicer home to live in. Win win.

If you have any questions about either a refinance or a refinance plus improvements, and what each of these would look like given your financial situation, please don't hesitate to contact me anytime, I'd love to work with you!
LISA MANWARING

MORTGAGE EXPERT

LET'S TALK

RECENT POSTS


By Lisa Manwaring • November 11, 2026
What Lenders Mean by “Good Credit” When You Apply for a Mortgage Credit is simply the ability to borrow money today based on the trust that you’ll repay it in the future. When you apply for a mortgage, lenders want proof that you’ve consistently honoured that trust by managing credit responsibly. But what does a good credit history actually look like to a lender? The 2 / 2 / 2 Rule Explained If you’re newer to credit or want a simple way to remember minimum mortgage credit requirements, think of the 2 / 2 / 2 rule: 2 active trade lines Established for at least 2 years With a minimum combined limit of $2,000 This is a common baseline lenders use when assessing credit for mortgage financing. What Counts as a Trade Line? A trade line is any account where credit is extended to you, such as: A credit card A line of credit A car loan A personal or installment loan Each trade line reports your payment history to the credit bureau and contributes to your credit score. For a trade line to be considered active , it must: Have been used at least once, and Show activity at least once every three months Why Time Matters Lenders want to see that you’ve managed credit responsibly over time , not just recently. Using two trade lines consistently for at least two years helps demonstrate stable financial habits and reliability. Understanding Credit Limits vs. Balances The credit limit is what matters—not the balance. For example: A $1,000 credit card + a $2,500 line of credit = $3,500 total limit This meets the minimum requirement You do not need to carry a balance to build credit. In fact, the best approach is to: Use your credit regularly Pay it off in full each month (for credit cards) Make all loan payments on time If your lender offers a credit limit increase and you’re managing credit well, it’s often a good idea to accept it. Higher limits—used responsibly—can strengthen your credit profile. A Simple Way to Build Credit Automatically One effective strategy is to: Put recurring bills on your credit card Set up an automatic transfer to pay the balance in full every month Automation helps build positive credit history without requiring constant attention—just be sure to monitor your accounts to ensure everything runs smoothly. What About Credit Scores? Yes, credit scores matter—but they’re not the whole story. If you: Have two active trade lines Established for two years With at least $2,000 in total limits And no missed payments …your credit score will generally take care of itself. That said, it’s still wise to review your credit report occasionally to check for errors or unfamiliar accounts. Final Thoughts If you’re thinking about buying a home in the next couple of years, now is the perfect time to review your credit and make sure you’re on track. Small adjustments today can make a big difference when it’s time to apply for a mortgage. If you’d like help reviewing your credit or understanding how it affects your mortgage options, feel free to connect anytime. I’d be happy to walk through it with you and help you plan with confidence.
By Lisa Manwaring • November 4, 2026
Can’t Find the Right Home After You’re Pre-Approved? There’s Another Option The best place to start any home purchase is with a mortgage pre-approval. It gives you clarity around your budget and lets you shop with confidence. But what happens when you’ve been pre-approved, you know where you want to live—and nothing suitable fits your price range? This is a common challenge, especially for first-time homebuyers. Before buyer fatigue sets in, it may be worth considering a different approach: buying a home that needs work and financing the renovations as part of your mortgage . What Is a Purchase Plus Improvements Mortgage? A purchase plus improvements program allows you to buy a property and include the cost of approved renovations directly in your mortgage. This can be a great solution if: You can’t find a move-in-ready home within budget You’re open to renovations You want to customize the home from the start It opens up more options and can help you get into a location or property that would otherwise be out of reach. How the Process Works While the idea is straightforward, the process itself is structured and requires planning. Here’s a high-level overview: Renovation quotes are required upfront You’ll need detailed quotes for the work you want completed before final mortgage approval. Renovations must add value The lender must be satisfied that the improvements will increase the property’s value accordingly. Funds are reimbursed, not advanced You pay for the renovations initially. Once the work is completed and verified by an appraiser, the lender reimburses you and adds the cost to your mortgage. With the right guidance, this process is very manageable—but it’s important to understand the steps before committing. Is This Program Right for You? Purchase plus improvements isn’t for everyone. Buying a home is already a big undertaking, and adding renovations can increase stress—especially if timelines, budgets, or contractors become challenging. That said, if you’re financially prepared and like the idea of shaping the home to fit your needs, this program can be an excellent way to get more value and flexibility from your purchase. Final Thoughts If you’re struggling to find the right home after being pre-approved, you may not need to lower your expectations—you may just need a different strategy. If you’d like to explore whether a purchase plus improvements mortgage makes sense for you, feel free to connect. I’d be happy to walk you through the process and outline exactly what this option would look like in your situation.